The Hidden Costs of Owning a Home in Oklahoma City
October 30, 2026
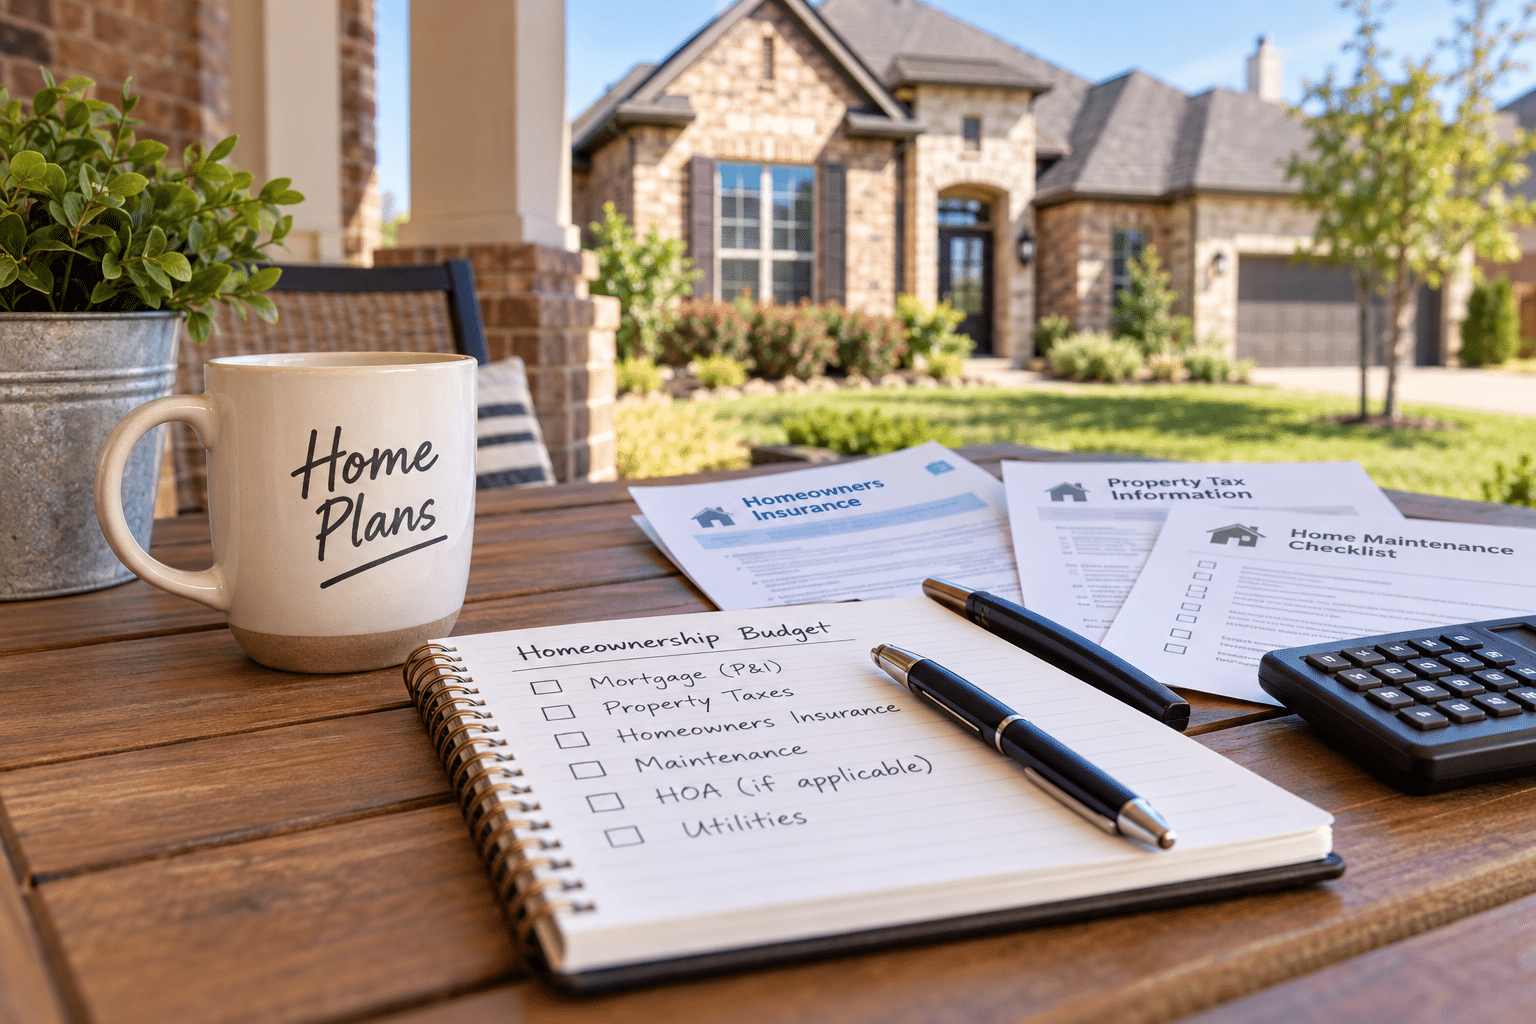
The mortgage payment gets most of the attention when people shop for a home. But it isn’t necessarily the expense that catches a new homeowner off guard.
Sometimes it’s the first homeowners insurance renewal. Other times, it’s an unexpected repair, a property tax adjustment, or discovering how much regular upkeep actually costs.
These expenses aren’t unusual. They’re part of owning a home. The challenge is making sure they’re included in the budget before you buy.
For buyers in Oklahoma City, Edmond, Deer Creek, and surrounding communities, understanding the hidden costs of homeownership can make the difference between a comfortable monthly budget and one that feels tighter than expected.
What Does It Really Cost to Own a Home?
A 2026 analysis from Zillow and Thumbtack estimates that the typical U.S. homeowner faces $16,566 annually in maintenance, property taxes, and homeowners insurance beyond the mortgage principal and interest.
That works out to approximately $1,381 per month.
Here’s how the national estimate breaks down:
| Expense | Annual Cost | Monthly Equivalent |
|---|---|---|
| Home maintenance | $11,171 | $931 |
| Property taxes | $3,129 | $261 |
| Homeowners insurance | $2,266 | $189 |
| Total | $16,566 | $1,381 |
These are national estimates, not a prediction of what a particular Oklahoma City home will cost.
The analysis also includes property taxes and insurance, which many homeowners already pay through their monthly mortgage escrow accounts. Those expenses shouldn’t be counted twice when building a budget.
The important point is that a mortgage principal-and-interest payment doesn’t tell the whole story.
Why Homeowners Insurance Deserves Special Attention in Oklahoma
Of the three expenses examined in the Zillow and Thumbtack report, homeowners insurance experienced the largest percentage increase over the previous five years.
The report estimates that insurance costs rose 54% nationally during that period, compared with 32% for maintenance and 19% for property taxes.
That’s particularly relevant to buyers in central Oklahoma.
Severe thunderstorms, hail, high winds, and tornado exposure are familiar considerations here. Insurance companies evaluate these risks along with the home’s age, construction, roof condition, replacement cost, and other factors when determining premiums.
Two similarly priced homes can have noticeably different insurance costs.
For example, a house with an older roof may present a different insurance situation than a comparable property with a recently replaced roof. The age of the roof, its material, and the insurer’s underwriting requirements can all affect coverage and pricing.
That’s why we encourage buyers to investigate insurance costs early rather than treating them as a detail to handle shortly before closing.
An insurance quote should be part of evaluating a home, not simply a closing checklist item.
It’s also worth understanding what the policy covers.
Wind and hail deductibles may be calculated differently from other deductibles, sometimes as a percentage of the insured dwelling value. Buyers should also ask whether roof claims are settled on a replacement-cost or actual-cash-value basis.
Those details can matter considerably when a claim occurs.
Property Taxes: Look Beyond What the Seller Pays
Property taxes are another area where buyers can misunderstand the cost of ownership.
In Oklahoma County and surrounding counties, property tax amounts depend on factors that include the property’s taxable value, applicable exemptions, and local taxing jurisdictions.
One important distinction is that the seller’s current tax bill may not reflect what the buyer will eventually pay.
The seller may qualify for exemptions or valuation limitations that won’t apply to the new owner. Changes in ownership and property valuation can also affect future taxes under Oklahoma law.
This is especially worth reviewing when purchasing new construction.
A property may have a tax history based partly on the land or on an earlier stage of construction. That historical amount may not represent the taxes associated with the completed home.
Before buying, review the property’s tax information with your real estate agent and lender. The county assessor can help clarify valuation and exemption questions.
A reasonable estimate of future property taxes is much more useful than simply copying the amount from the current listing.
Home Maintenance Is Usually the Largest Expense
Maintenance accounts for approximately two-thirds of the annual hidden costs identified in the Zillow and Thumbtack study.
That doesn’t mean every homeowner will spend $11,171 each year.
Maintenance varies significantly with the size, age, condition, and features of a property.
Consider the differences between a smaller home in Northwest Oklahoma City and a larger property in Edmond with extensive landscaping, multiple heating and cooling systems, a swimming pool, and a substantial roof.
Even if both homes are in excellent condition, their ongoing maintenance requirements will be different.
Some expenses are predictable: HVAC servicing, lawn care, irrigation adjustments, gutter cleaning, and routine repairs.
Others are less predictable. A water heater can fail, an air-conditioning system can need replacement, or a roof can require work earlier than expected.
One distinction we encourage buyers to make is between routine maintenance and major capital replacements.
Routine maintenance keeps a home operating properly. Major replacements, such as a roof or HVAC system, may require substantially larger amounts of money at irregular intervals.
A sound ownership budget makes room for both.
New Construction Doesn’t Eliminate Ownership Costs
New construction can reduce certain maintenance concerns during the first few years, particularly when major components are new and covered by applicable warranties.
But new homes aren’t maintenance-free.
Landscaping, irrigation systems, drainage, HVAC servicing, and ordinary upkeep still require attention.
Buyers should also consider expenses that may not be included in the purchase price, such as window coverings, fencing, additional landscaping, or other improvements.
In some Edmond and Deer Creek communities, homeowners association dues may cover certain services. In others, owners are responsible for nearly everything.
Understanding what an HOA actually maintains is just as important as knowing the amount of its dues.
A lower-maintenance home can be an excellent choice, but it’s important to understand exactly what that means for the particular property.
How Much Should You Set Aside for Home Maintenance?
There’s no single formula that works for every home.
A commonly used starting point is to reserve approximately 1% of a home’s value annually for maintenance and repairs. Some properties will require less, while older or more complex homes may require considerably more.
For illustration:
| Home Value | 1% Annual Reserve | Monthly Savings |
|---|---|---|
| $300,000 | $3,000 | $250 |
| $400,000 | $4,000 | $333 |
| $600,000 | $6,000 | $500 |
| $1,000,000 | $10,000 | $833 |
This is a budgeting guideline, not a forecast of actual expenses. It also shouldn’t be confused with the Zillow and Thumbtack estimate, which uses a different methodology.
A property’s condition matters more than any simple percentage.
A well-maintained older home with recently replaced mechanical systems might require less near-term spending than a newer home with extensive outdoor amenities.
A professional home inspection can help identify concerns, although it cannot predict every future repair.
For buyers considering higher-end properties, it’s especially important to evaluate the costs of pools, multiple HVAC systems, extensive landscaping, and specialty equipment individually.
Five Steps to Build a More Realistic Homeownership Budget
Before deciding what price range feels comfortable, we recommend looking at the complete cost of living in the home.
1. Estimate the full monthly housing payment. Include principal, interest, property taxes, homeowners insurance, applicable mortgage insurance, and HOA dues. Confirm which expenses are already included in the lender’s payment estimate.
2. Request insurance quotes early. Provide the insurance agent with information about the specific property, particularly its roof, age, construction, and replacement cost. Compare coverage and deductibles, not just premiums.
3. Review the property’s tax situation. Understand existing exemptions and whether the current tax amount is a reasonable guide to future ownership costs.
4. Evaluate maintenance needs before closing. Review inspection findings, the age of major systems, the roof, drainage, and any additional amenities requiring ongoing care.
5. Maintain a separate reserve for repairs and replacements. Even a carefully inspected home can have unexpected expenses. Setting money aside regularly makes those costs easier to manage.
These steps don’t eliminate every surprise, but they provide a much clearer understanding of what a home will require financially.
Buying a Home You Can Comfortably Maintain
After years of helping buyers throughout the Oklahoma City area, one principle remains important to our approach: finding the right home involves more than qualifying for the mortgage.
A lender can help determine what you may be able to borrow. The more personal question is what level of ongoing housing expense fits comfortably within your financial plans.
Those aren’t always the same number.
A home with a slightly lower purchase price but substantial maintenance needs may ultimately cost more to own than another property requiring less attention.
Likewise, a larger home may fit comfortably within the purchase budget while introducing ownership expenses that deserve careful consideration.
The goal isn’t to discourage anyone from buying a home they love. It’s to understand the financial commitment before making that decision.
The best homeownership budget accounts for the house long after closing day.
If you’re considering a home in Oklahoma City, Edmond, or the surrounding communities, Bill and I are happy to help you evaluate the property’s condition, ownership considerations, and questions worth asking before making an offer.
For specific insurance, tax, and financial projections, we’ll encourage you to work with the appropriate qualified professionals.
A little more preparation now can make owning the home much more comfortable later.
REALTOR® at McGraw Realtors
Heather Wall helps buyers and sellers throughout the Oklahoma City metro, with a focus on Edmond, Deer Creek, and Northwest Oklahoma City. As part of OKCHomeSellers at McGraw Realtors, she works alongside her father, Bill Wilson, combining attentive communication, practical guidance, and local market knowledge to help clients make confident real estate decisions.